DMCI Homes now accepts Pag-IBIG Fund housing loans for the balance on its ready-for-occupancy condos — Allegra Garden Place (Pasig), The Oriana North Tower (Quezon City) and all Legacy Projects — and Pag-IBIG financing will also be available at The Erin Heights (Quezon City). It joins spot cash, bank financing and DMCI in-house financing as a fourth way to pay.
Pag-IBIG lends up to ₱10 million for up to 30 years. Until December 31, 2026 it is running promotional rates of 4.5% on loans up to ₱4.9 million and 5.75% above that, fixed for three years. On a real Allegra studio that is ₱23,245 a month — about ₱13,713 less than the same balance on a typical bank loan.
For years, whenever a buyer asked me “Can I use my Pag-IBIG?” I gave the same answer: DMCI is spot cash, bank or in-house. Pick one.
That answer just changed. DMCI Homes has made Pag-IBIG financing official on its ready-for-occupancy projects — Allegra Garden Place, The Oriana and every one of its Legacy Projects — and it is extending the same option to The Erin Heights.
This matters more than any discount I have announced this year, because of who it reaches. Every employed Filipino pays into Pag-IBIG. Every OFW has been required to since 2009. Millions of people have years of contributions sitting in the Fund, and until now, none of it could touch a DMCI unit.
I am Kris Chavez, DMCI Homes Accredited In-House Senior Property Consultant since 2016. Below is what changed, which units it applies to today, what it does to your monthly — computed on real units from DMCI’s October 15 availability list — and the one Pag-IBIG rule that can quietly cost you ₱4,000 a month if nobody points it out.
Pag-IBIG Fund and DHSUD hold the National Housing Expo on October 19 and 20, 2026 at the SMX Convention Center, Pasay — and DMCI Homes is one of the participating developers. If you want your loan computed on a specific DMCI unit before you go, message me first.
Which DMCI Projects Accept Pag-IBIG
Three groups, and they work slightly differently.
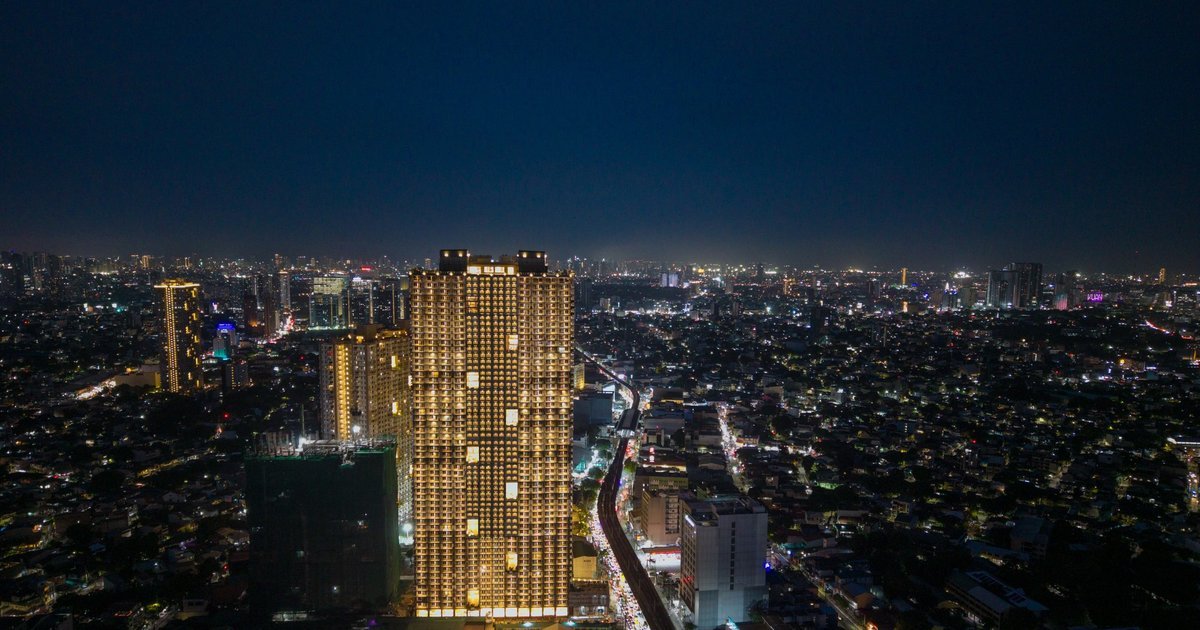
The Legacy Projects — every one of them
DMCI’s Legacy Projects are its older, finished communities, and they are also where the year’s biggest discount lives: 20% off until November 30, 2026. Pag-IBIG financing now applies across the whole list:
Why This Is Big News for OFWs — and Everyone Who Pays Pag-IBIG
Pag-IBIG is not something most people chose. It comes off the payslip — usually ₱200 a month, matched by the employer — and for overseas Filipino workers it has been mandatory since Republic Act 9679 took effect in 2010. Which means if you have worked for even two years, you very likely already qualify on the contribution count. The Fund asks for 24 monthly contributions.
For an OFW, three things make this better than a bank:
- You are already a member. There is no new relationship to build with a lender who does not know you; your contribution record is the relationship.
- The monthly is lower — a lower rate and a longer term, which is exactly what you need when you are budgeting a home in pesos on a salary earned somewhere else.
- You do not need to fly home. A family member here signs for you under a Special Power of Attorney, and I run the DMCI side of the file — reservation, downpayment schedule, documents and turnover.
“If you have been paying Pag-IBIG for years and wondering what you were paying for — this is it.”
Pag-IBIG vs Bank: The Same Unit, Side by Side
Two real, available two-bedrooms. Both computed on DMCI’s 12% downpayment term with the regular 1% discount, so Pag-IBIG (or the bank) is financing the 88% balance.
| Allegra · Soraya 309 | The Oriana · North 405 | |
|---|---|---|
| Unit | 2BR · 55 sqm | 2BR · 54.5 sqm |
| List price | ₱7,748,000 | ₱7,501,000 |
| After 1% discount | ₱7,670,520 | ₱7,425,990 |
| 12% downpayment | ₱920,462 ₱27,827/mo × 32 after ₱30,000 reservation | ₱891,119 ₱26,910/mo × 32 after ₱30,000 reservation |
| Balance to finance (88%) | ₱6,750,058 | ₱6,534,871 |
| Pag-IBIG · 5.75% · 30 years | ₱39,392/mo | ₱38,136/mo |
| Bank · 7.5% · 20 years (indicative) | ₱54,378/mo | ₱52,644/mo |
| Monthly difference | ₱14,987 less | ₱14,509 less |
| Gross household income to carry it (≈35% rule) | ₱112,547 vs ₱155,366 | ₱108,959 vs ₱150,413 |
List prices from DMCI’s availability list dated October 15, 2026. Bank shown at an indicative 7.5% fixed over 20 years — the range most buyers are being quoted after the September rate hike. Your actual rate is set at approval.
The last row is the one I would read twice. Qualifying for a loan is about whether the monthly fits your income. On the Allegra 2BR, the bank route needs roughly ₱155,366 a month in household income; Pag-IBIG needs about ₱112,547. For a lot of families, that is the difference between “not yet” and “yes.”
The honest part
Some of that monthly gap is the rate, and some of it is the extra ten years. If you put Pag-IBIG on the same 20-year term as the bank, the Allegra 2BR is ₱47,391 a month — still ₱6,987 less from the rate alone. But a 30-year loan pays interest for longer: at today’s numbers, about ₱14,181,120 over 30 years versus ₱13,050,720 over 20. Pag-IBIG wins on the monthly and on qualifying. If you can afford to pay more than the minimum, tell me — I will show you how to structure it so you also win on the total.
The ₱4.9 Million Line Nobody Will Tell You About
Pag-IBIG’s two promo rates are split by loan size: 4.5% up to ₱4.9 million, 5.75% above it. Which means a buyer who is only a little over the line pays the higher rate on the whole loan.
Allegra Garden Place, Amina 919 — a 30 sqm one-bedroom at ₱5,710,000. On the 12% term the balance is ₱4,974,552. That is ₱74,552 over the line, so it prices at 5.75%: ₱29,030 a month.
Pay that ₱74,552 as extra downpayment. The loan drops to exactly ₱4,900,000, it qualifies for 4.5%, and the monthly falls to ₱24,828 — ₱4,202 a month less, or ₱151,272 over the three-year fixed period, for ₱74,552 paid upfront.
Same story at Cypress Towers (Legacy, 20% off): Celesta PH10 leaves a ₱4,951,232 balance — ₱51,232 over the line — and pulling it under saves ₱4,066 a month. When I compute your unit, this is the first thing I check. Confirm the bracket on your own loan with Pag-IBIG when you file; I will go through it with you.
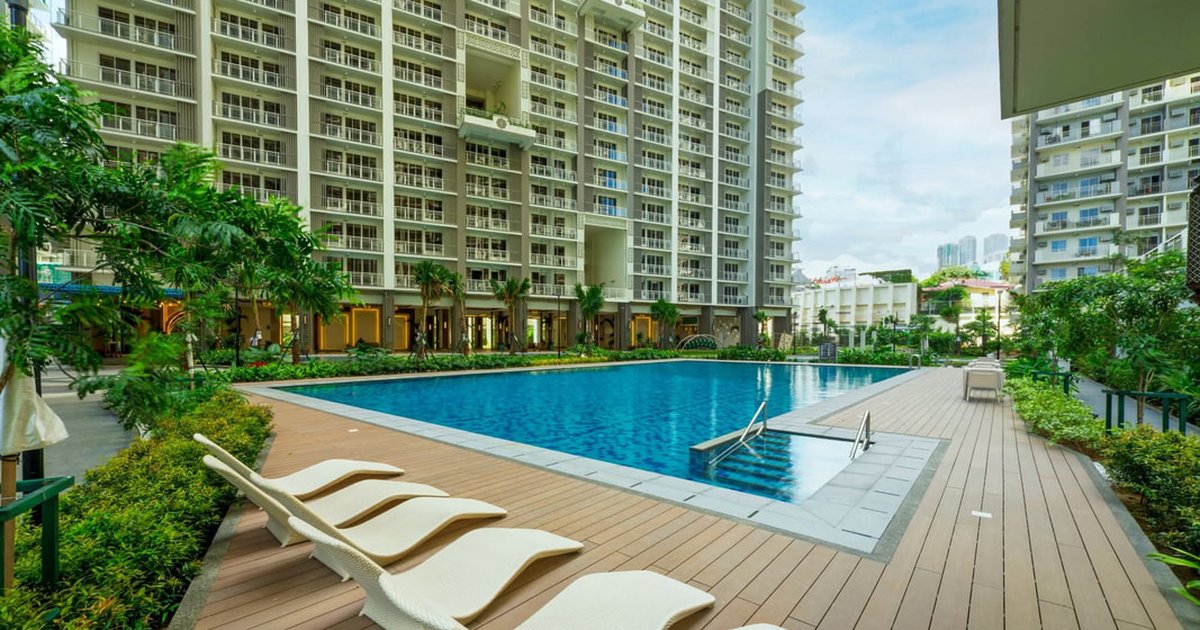
Allegra Garden Place, Pasig
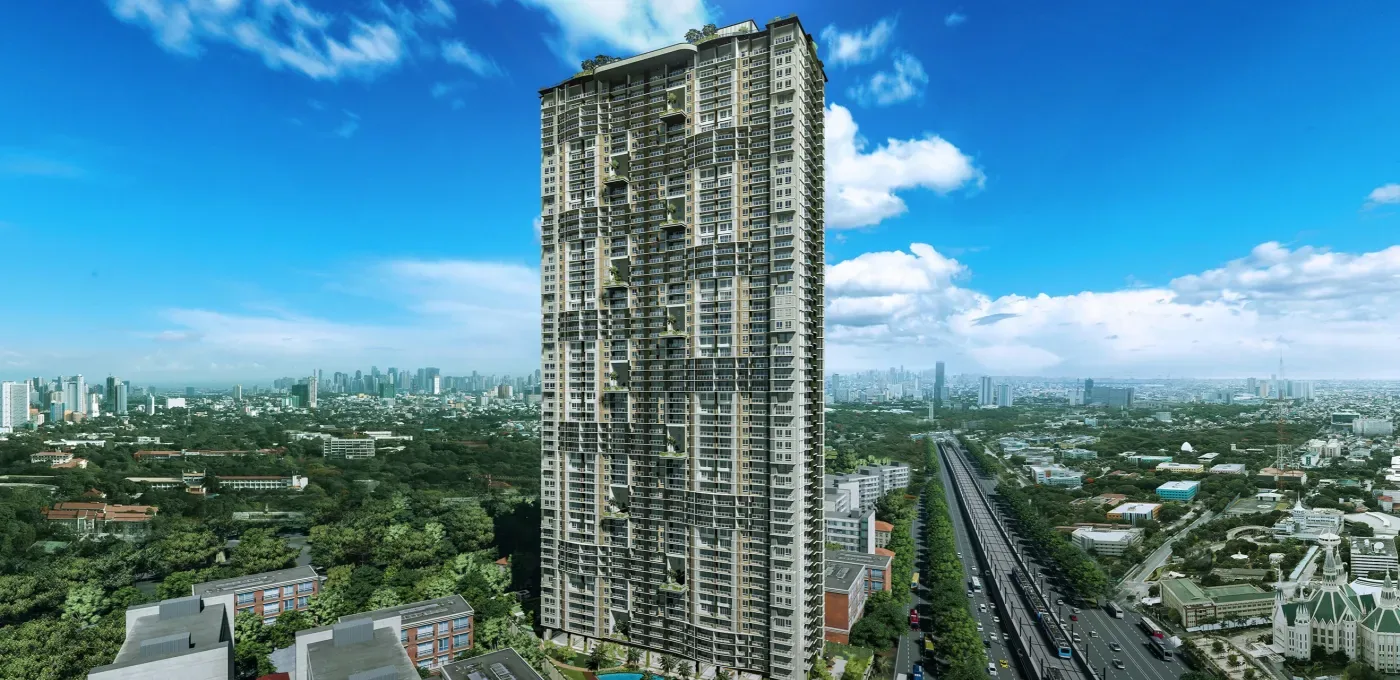
Two 55-storey Modern Moroccan towers — Amina and Soraya — on Pasig Boulevard, 110 metres from Rizal Medical Center, 3.3 km from Ortigas Center. Both towers are finished and turned over, and DMCI’s October 15 list shows 744 units open, from studios to a single remaining 3-bedroom.
| Unit | List price | Pag-IBIG / mo | Bank / mo |
|---|---|---|---|
| Soraya 2417 · Studio · 30 sqm | ₱5,266,000 | ₱23,245 4.5% | ₱36,959 |
| Amina 919 · 1BR · 30 sqm | ₱5,710,000 | ₱29,030 5.75% | ₱40,075 |
| Soraya 309 · 2BR · 55 sqm | ₱7,748,000 | ₱39,392 5.75% | ₱54,378 |
The studio is the headline: a finished, move-in-ready Pasig address on a Pag-IBIG loan of ₱23,245 a month. Allegra also runs DMCI’s Christmas Countdown — an extra 1.5% off for October reservations, 1% in November — which comes on top of the figures above and lowers them further.
The Oriana North Tower, Quezon City
A 54-storey tower on Aurora Boulevard, Project 4 — 390 metres to LRT-2, with Anonas, Katipunan and Cubao stations minutes away. The North Tower is ready for occupancy and is where Pag-IBIG financing applies today; 329 two-bedrooms are open on DMCI’s October 15 list.
| Unit | List price | Pag-IBIG / mo | Bank / mo |
|---|---|---|---|
| North 1906B · 1BR · 29 sqm | ₱5,109,000 | ₱22,552 4.5% | ₱35,857 |
| North 405 · 2BR · 54.5 sqm | ₱7,501,000 | ₱38,136 5.75% | ₱52,644 |
North 1906B is the only one-bedroom left in the North Tower. On Pag-IBIG it is ₱22,552 a month, and the balance sits under the ₱4.9 million line, so it gets the 4.5% rate without any adjustment.
The Legacy Projects: 20% Off, Then Pag-IBIG
This is where the two pieces of news stack. The Legacy discount takes 20% off the price, and Pag-IBIG finances what is left — which pushes most of these balances under the ₱4.9 million line and onto the 4.5% rate. These are the actual units open on DMCI’s October 15 list:
| Community · unit | Price after 20% | Pag-IBIG rate | Pag-IBIG / mo | Bank / mo |
|---|---|---|---|---|
| Mayfield Park Residences Mandala 213 · 2BR · 42 sqm · Pasig | ₱3,504,000 | 4.50% | ₱15,624 | ₱24,841 |
| Raya Gardens Condominium Surabaya 432 · Studio · 31 sqm · Parañaque | ₱3,442,400 | 4.50% | ₱15,349 | ₱24,404 |
| Maricello Villas Almeria 103 · 2BR · 53 sqm · — | ₱4,530,400 | 4.50% | ₱20,200 | ₱32,117 |
| Alea Residences Budi 304 · 2BR · 55 sqm · Bacoor, Cavite | ₱5,074,400 | 4.50% | ₱22,626 | ₱35,974 |
| Rhapsody Residences Viola 302 · 2BR · 55.5 sqm · Muntinlupa | ₱5,484,000 | 4.50% | ₱24,452 | ₱38,877 |
| Cypress Towers Celesta PH10 · 2BR · 48 sqm · Taguig (C-5) | ₱5,626,400 | 5.75% | ₱28,894 | ₱39,887 |
| East Raya Gardens Banyan 116 · 2BR · 62.5 sqm · Pasig | ₱5,910,400 | 5.75% | ₱30,353 | ₱41,900 |
| Alea Residences Raja 711 · 3BR · 85.5 sqm · Bacoor, Cavite | ₱7,154,400 | 5.75% | ₱36,741 | ₱50,719 |
20% Legacy Projects special discount per DMCI memo PD-26-05-026, units only, until November 30, 2026; no other discount stacks on top. Illumina, Ivory Wood, Mirea, Royal Palm, Tivoli, Willow Park, East Ortigas Mansions, Magnolia Place and Riverfront are on the qualifying list but had no open units on the October 15 list — legacy units resurface on DMCI’s reopened lists, so ask me.
A two-bedroom at Mayfield Park in Pasig for ₱15,624 a month. A two-bedroom at Alea Residences in Bacoor for ₱22,626. Those are the lowest DMCI monthlies I have computed this year — and the 20% ends on November 30.
The Erin Heights: Pay the Downpayment Now, Pag-IBIG Later
The Erin Heights is still being built — 66% complete as of July 2026, turnover scheduled for October 2027 — on Commonwealth Avenue corner Tandang Sora, 1.1 km from UP Diliman. It works differently: you pay the 12% downpayment over 32 months, and Pag-IBIG takes out the 88% balance after that.
| Unit | List price | Downpayment / mo | Pag-IBIG / mo (6.25%) |
|---|---|---|---|
| Erin 3103 · Studio · 28.5 sqm | ₱5,391,000 | ₱19,077 | ₱28,918 |
| Erin 704 · 2BR · 48.5 sqm | ₱7,434,000 | ₱26,661 | ₱39,877 |
| Erin 601 · 3BR · 84 sqm | ₱11,264,000 | ₱40,880 | ₱60,422 |
One honest caveat: the 4.5% and 5.75% promo rates are for applications filed until December 31, 2026, and your Erin Heights loan is filed later. So I have computed it at 6.25% — Pag-IBIG’s rate before the promo — rather than promise you a rate that may not exist by then. If Pag-IBIG extends the promo, your monthly only goes down. The 3BR loan (₱9,813,197) also sits inside the ₱10 million cap.
Do You Qualify?
- 24 monthly contributions posted — check them on Virtual Pag-IBIG.
- Age: 65 or younger when you apply, and 70 or younger when the loan matures (so a 50-year-old can take up to 20 years).
- Income that carries the monthly — as a working rule, keep the amortization within about 35% of gross household income. Co-borrowers can be combined.
- No foreclosed, cancelled or bought-back Pag-IBIG housing loan in your name.
- Loan within ₱10 million and within Pag-IBIG’s appraisal of the unit.
How to Buy a DMCI Unit With Pag-IBIG Financing
- Send me your contribution count and budget. I match you to units and compute Pag-IBIG against the bank on each — including the ₱4.9M line check.
- Reserve with ₱30,000. The unit comes off the market and your price is locked.
- Pay the 12% downpayment. On DMCI’s schedule — 32 months at Allegra, The Oriana and The Erin Heights.
- File your Pag-IBIG housing loan. I prepare the DMCI documents Pag-IBIG asks for; OFWs file through a Special Power of Attorney.
- Pag-IBIG appraises and approves. It values the unit, approves your loan and issues its approval and guaranty to DMCI.
- Pag-IBIG releases the loan to DMCI. From here you pay Pag-IBIG instead of DMCI. On ready-for-occupancy units, turnover follows once your account clears.
What Pag-IBIG Financing Doesn’t Do
Good to know
- Lower monthly and easier to qualify than most bank loans.
- Works with the Legacy 20% discount and the Christmas Countdown — they reduce the price; Pag-IBIG finances the balance.
- Contribution history counts — no new lender relationship to build.
Watch out for
- The promo rate is fixed for 3 years, then reprices.
- Pag-IBIG lends against its own appraisal, which can come in under DMCI’s price.
- The 5% downpayment RFO promo is Chinabank/BPI only — Pag-IBIG buyers use the 12% term.
Questions I’m Getting About Pag-IBIG at DMCI
Sources
- Pag-IBIG Fund raises limit on housing loans to ₱10 million — Philstar, May 29, 2026
- 4.5% promotional rate on loans up to ₱4.9 million; 5.75% above, up to ₱10 million — Daily Tribune, July 8, 2026
- Promo rates valid until December 31, 2026; National Housing Expo October 19–20 with DMCI Homes participating — Daily Tribune, October 2026
- Mandatory Pag-IBIG membership for overseas Filipino workers — Republic Act No. 9679, the Home Development Mutual Fund Law of 2009
- Unit prices and availability — DMCI Homes availability list dated October 15, 2026; Legacy discount per DMCI memo PD-26-05-026
Send me your contribution count — I’ll do the rest
Tell me how many months of Pag-IBIG you have and the project you like. I will send back the real unit, the Pag-IBIG monthly against the bank, and whether you are on the right side of the ₱4.9M line — usually within the hour.